
- Home
- Blog
- Forecast and Price Predictions
- Forex Market Outlook Q4 2026: The Dollar Decides
Forex Market Outlook Q4 2026: The Dollar Decides

This article breaks down the currency chapter of NAGA's Q4 2026 Market Outlook, "The Dollar Decides", by Frank Walbaum, Market Analyst at NAGA. The full report, with 20 charts, three scenarios, and a quarter-long calendar, is available as a free PDF.
Forex market outlook Q4 2026 — key takeaways
The outlook's view on the four main currency markets for Q4 2026, at a glance:
- US Dollar Index (DXY): bullish, correction possible. Key level 102.50; driven by the Fed path, US data and the yield gap.
- EUR/USD: bearish, vulnerable. Key level 1.1150; driven by the Fed vs. the ECB and French fiscal risk.
- GBP/USD: neutral, a Budget test. Key levels 1.3140 and 1.3311; driven by the BoE vs. the Fed, the 28 October Budget and gilts.
- USD/JPY: bullish, with intervention risk. Key levels 160 and 164; driven by the US–Japan rate gap and a firm dollar.
Each view, the scenarios behind it and the dates that could change it are explained below.
Source: NAGA Q4 2026 Market Outlook. The bias reflects the author's directional view and is not a recommendation.Open an account Practice on demo Copy lead traders
CFD trading involves risk.
Q3 2026 review: a flat quarter, then a sharp dollar rebound
The US dollar finished Q3 almost unchanged, but the quarter ended very differently from how it began. The DXY rose just 0.2% between 1 July and 30 September and is up 3.4% for the year, while EUR/USD and GBP/USD ended almost flat and USD/JPY fell 3.2%.
Market Q3 2026 YTD 2026 US Dollar Index (DXY) +0.2% +3.4% EUR/USD −0.3% −3.1% GBP/USD +0.1% −1.5% USD/JPY −3.2% +0.6% Source: NAGA trading platform. Q3 = 1 July open to 30 September close; YTD = 1 January open to 30 September close. Past performance is not a reliable indicator of future results.
The real move came late. The index climbed from a low of 98.79 on 8 September to 102.54 intraday on 5 October, a gain of almost 4% in less than a month. Two events shaped the backdrop: the Fed raised rates on 16 September for the first time since 2023, and Japan intervened to support the yen after USD/JPY reached 163.99 in July, joined by the US in the first joint intervention since 1998.
US dollar outlook: bullish trend, but a correction is possible
In Frank Walbaum's view, the long-term trend of the US dollar remains bullish. The 102.50 area has become the key technical reference, and a sustained breakout above it would confirm that the trend is continuing. On the weekly chart, the rebound has reached the top of the 2025–26 rising channel near 102.
The rally has also become stretched, so a temporary retracement is part of the Q4 outlook and would not on its own invalidate the trend. Stronger US data would support the dollar by reinforcing expectations of further tightening and keeping US yields attractive. Weaker data could create temporary dollar weakness and help risk assets, commodities and crypto.
The Fed is the swing factor. Its September projections imply one more 25-basis-point hike in 2026, while September payrolls rose by only 29,000 and unemployment edged up to 4.2%. Frank Walbaum sets out his base case:
"I expect the Fed to hold in October and hike again in December — the September projections point to one more hike this year, while the latest market pricing strongly favours an October hold followed by a December move." — Frank Walbaum, Market Analyst, NAGA
Central banks: a world of rate hikes drives currencies
Central bank policy is the engine of the currency market in Q4. September brought hikes from the Fed, the ECB and the Bank of Japan, while three Bank of England policymakers voted for a hike, largely in response to energy-driven inflation.
Central bank Policy rate Last decision Q4 meetings Federal Reserve 3.75–4.00% +25 bp, 16 September 27–28 October · 8–9 December European Central Bank 2.50% (deposit) +25 bp, 10 September 29 October · 17 December Bank of Japan 1.25% +25 bp, 18 September 29–30 October · 17–18 December Bank of England 3.75% Hold, 17 September (6–3) 5 November · 17 December Sources: Federal Reserve, ECB, Bank of Japan, Bank of England.
Relative policy paths, above all between the Fed, the ECB and the Bank of Japan, feed directly into the currency outlook. NAGA's Interest Rates Forecast follows the policy outlook as the quarter unfolds.
EUR/USD forecast: 1.1150 is the line in the sand
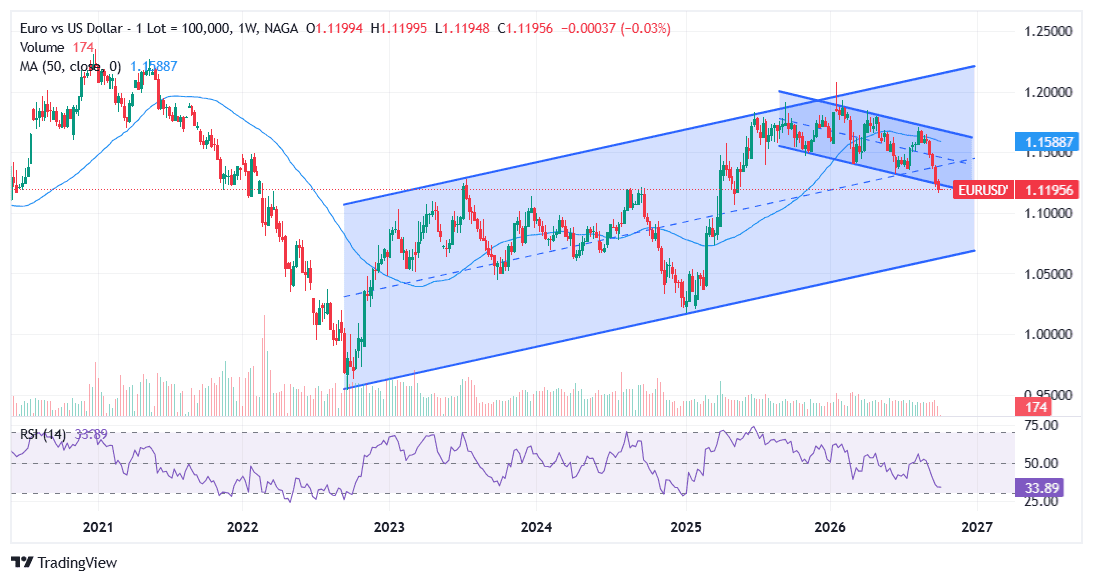
EUR/USD is the mirror image of the dollar story. The pair fell to 1.1161 in early October, its weakest level since May 2025, down from an August high of 1.1699. The ECB has raised rates twice this year, yet French fiscal and political risk, an energy shock that weighs more heavily on Europe and a Fed that is also tightening have held the euro back.
Past performance is not indicative of future results.
The pair remains vulnerable while the dollar keeps a firm tone, and the ECB meetings on 29 October and 17 December are the key event risks. A more hawkish ECB could slow the decline, but rallies may struggle to gain traction as long as the broader dollar trend holds.
"1.1150 is the line in the sand — below it, the correction could turn into a proper downslide." — Frank Walbaum, Market Analyst, NAGA
The pair-by-pair view continues in NAGA's Euro to Dollar Forecast and Price Prediction.
USD/JPY outlook: 160 and the risk of intervention
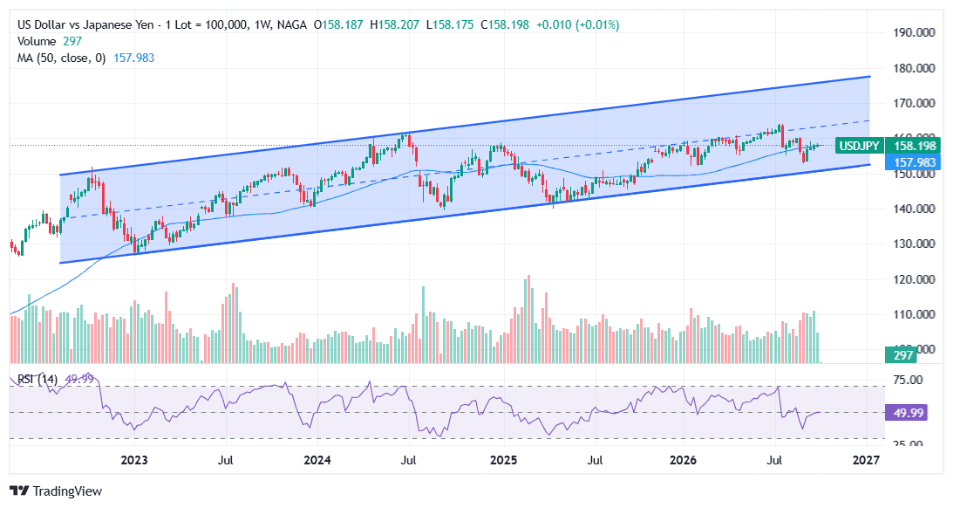
USD/JPY remains structurally bullish over the longer term, with 160 as the major reference point. As long as the broader trend holds and the dollar stays firm, a break above the recent highs could open the way for further upside.
Past performance is not indicative of future results.
That level has a history. The pair reached 163.99 on 23 July before Japan intervened, joined by the US on 31 July, and the Bank of Japan raised its policy rate to 1.25% on 18 September. Further BoJ decisions and intervention risk may cause sharp short-term swings, but they do not necessarily change the longer-term picture, so the outlook keeps a potential breakout on the radar if US data continues to favour the dollar.
British pound outlook: the 28 October Budget test
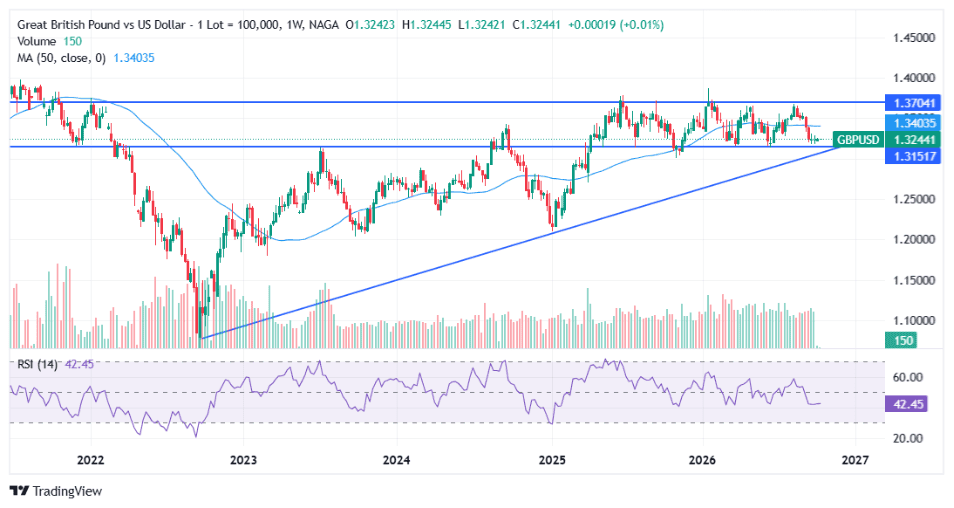
Sterling is caught between a Bank of England that is about to hike and a Fed that has already moved. GBP/USD rose just 0.1% in Q3 and is down 1.5% for the year to 30 September, and it slid through September towards its 2026 low of 1.3141, set on 24 June.
Past performance is not indicative of future results.
Chancellor John Healey's first Budget on 28 October is the pivot. The 10-year gilt yield reached 5.51% on 8 October, its highest since 2007. A package that reassures the gilt market could lift GBP/USD back towards its 50-week average near 1.3404, while a poorly received Budget would expose the 2026 low; a move back above 1.3311 would ease the pressure.
"Sterling is caught between a hawkish Bank of England and an even more hawkish Fed — the Budget on 28 October will decide whether 1.3140 holds." — Frank Walbaum, Market Analyst, NAGA
Against the euro, the pound looks sturdier: as long as EUR/GBP stays below 0.8535, French fiscal stress keeps sterling in favour. NAGA's Pound Forecast and Price Prediction covers sterling in more detail, including EUR/GBP.
Three scenarios for the dollar in Q4 2026
Rather than relying on a single forecast, NAGA's outlook works with three scenarios, each built around the dollar. Frank Walbaum sees a risk-off environment as the most likely outcome, with a 50% probability.
Scenario Probability Trigger What it means for currencies Dollar strength continues 25% DXY breaks above 102.50 Dollar stronger; USD/JPY potentially above 160 Dollar correction 25% Weaker US data, a more dovish Fed Dollar weaker; gold, stocks and crypto supported Risk-off environment 50% Weaker breadth, a fading AI narrative The dollar an important beneficiary; USD/JPY higher Directional expectations only; not a recommendation.
The dollar is supported in two of the three scenarios, and a firm dollar remains the outlook's base case. The signposts are hot CPI prints and hawkish FOMC meetings for the first scenario, weak payrolls for the second, and Big Tech results and bond yields above 5.5% for the third.
Key forex dates and levels for Q4 2026
The quarter is dense with event risk for currencies: three rounds of US inflation and jobs data, a UK Budget and five central bank decisions in December alone.
Date Event Why it matters 14 October US CPI (September) Key input for the Fed's December decision 28 October FOMC decision; UK Autumn Budget Fed guidance; gilts and GBP 29 October ECB decision Possible further hike; EUR/USD 30 October Bank of Japan decision USD/JPY, intervention risk 5 November Bank of England decision GBP, UK gilts 6 November US jobs report (October) Labour market vs. Fed 9 December FOMC decision with new projections The main event of the quarter 10 December Swiss National Bank decision CHF 17–18 December ECB, Bank of England and Bank of Japan decisions EUR, GBP, JPY
Market Support Resistance US Dollar Index (DXY) 99.25 (50-week average) 102.50 breakout EUR/USD 1.1150 1.1589 (50-week average) GBP/USD 1.3180, then 1.3140 1.3311, then 1.3404 (50-week average) USD/JPY 158 (50-week average) 160, then 163.99 Sources: Frank Walbaum; NAGA trading platform charts, beginning of October 2026. Dates subject to change.
The 9 December FOMC meeting, with its new projections, is likely to be the single most important event of the quarter for currencies. Levels are reference points, not targets: how price behaves around them, and which data arrives at the same time, matters more than the level itself.
More NAGA currency forecasts
This outlook sets the quarterly framework, while NAGA's forecast pages follow each currency in more detail and are updated as conditions change:
- Euro to Dollar Forecast and Price Prediction
- Pound Forecast and Price Prediction
- Turkish Lira Forecast and Price Prediction
- Indian Rupee Forecast and Price Prediction
- SAR to INR, AED to INR and Egyptian pound forecasts
- Interest Rates Forecast
The same quarter is covered for other markets in NAGA's stock market outlook, commodities outlook and crypto market outlook for 2026.


The present domain / website, NAGA.eu is owned by Naga Technology GmbH, however is independently and exclusively operated by Axon Securities S.A., an AEPEY which is authorised and regulated by the Hellenic Capital Market Commission (HCMC) under licence No. 7/560/02.09.2010 and with registered address 48 Stadiou Street, 105 64 Athens, Greece.
NAGA is a trade name and trademark under the NAGA Group AG, a German based FinTech company publicly listed on the Frankfurt Stock Exchange | WKN: A161NR | ISIN: DE000A161NR7. Exclusive rights for the use of the said trade name and trademark, in the territory of Greece, are exclusively granted to Axon Securities S.A. In this respect and for the avoidance of doubt, any references in the present domain to "NAGA" refer just to the brand/trade name/trademark, the NAGA Platform or account and not to any specific company under NAGA Group of companies.
RESTRICTED JURISDICTIONS:With regards to the current website, Axon Securities S.A. offers services to Greek residents. Axon Securities S.A does not provide investment and ancillary services in the territories of third countries including Japan, Canada and the USA. For further details please refer to our Terms & Conditions.
HIGH RISK INVESTMENT WARNING:CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. Between 74-89% of retail investor accounts lose money when trading CFDs. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Trading through an online platform carries additional risks. Refer to our Regulation section here.